
Menu
Close
Menu
Close


September 18, 2026
During the month of August, the Q2 reporting season concluded successfully for the Fund, featuring high-quality earnings results and providing additional support for our durable 2026 EPS growth forecast of 13%. The Fund has delivered three-month unit price growth of 4.8% net of fees, outperforming the benchmark by 2.2%.
We spent much of late 2025 and early 2026 discussing the indiscriminate de-rating of quality companies, driven by market fears of permanent disruption from artificial intelligence (AI). During this time, the market discarded even strong earnings reports from companies the market regarded to be ‘AI losers’. While this has been painful for Fund returns, we remained confident in our thesis that AI would become a tailwind for the Fund’s diversified collection of businesses, and that with mounting evidence of their continued dominance, alongside consistent earnings growth, they would eventually be rewarded by the market.
Pleasingly, the Q2 reporting season has featured early signs of a shift in the AI narrative for multiple portfolio holdings, particularly across the IT services space. While a shift in the broader AI narrative is unlikely to occur in a straight line, we have noticed that the market has begun appreciating that several Fairlight portfolio companies, who are leaders in their market niches, are in fact early adopters of AI. These companies are reaping the benefits of these long-term investments in AI, including winning market share and delivering strong earnings results in what are highly challenging macroeconomic conditions.
Fairlight Q2 reporting season results
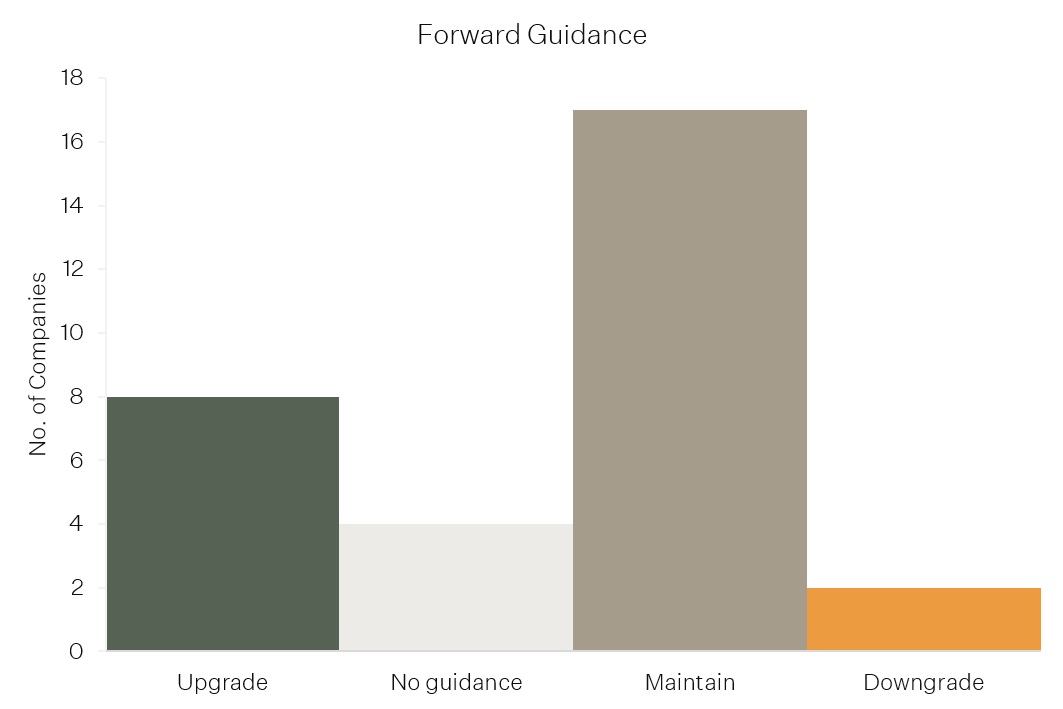
Reporting season has provided continued evidence of the quality of the earnings of portfolio companies, in addition to examples of tangible AI benefits. Q2 earnings either beat or met market expectations in 87% of cases (Figure 1) and Annual EPS guidance was upgraded or maintained for all portfolio companies, bar two which downgraded their forecasts for cyclical reasons (Figure 2).
Figure 1.
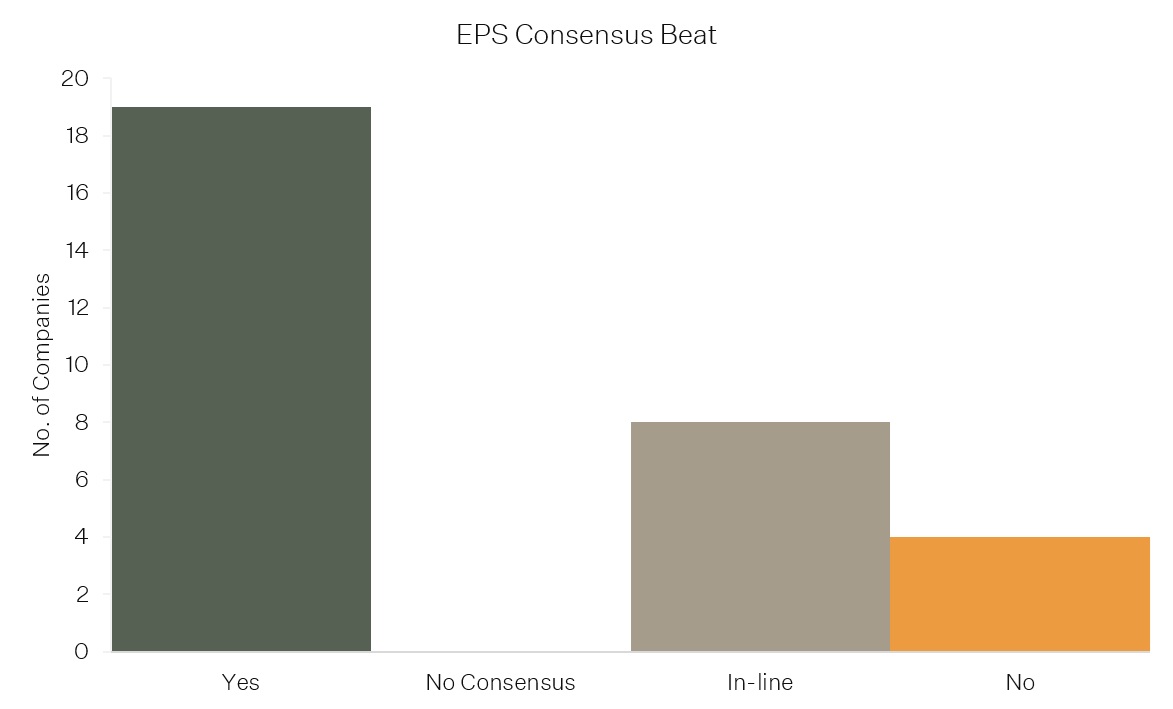
Figure 2.
This month, we highlight the results of portfolio holdings Softcat and Reply, where we have seen positive earnings multiple re-ratings as investors build confidence around the idea that these companies are quietly strengthening their competitive advantages rather than falling behind.
Softcat
Softcat is a leading IT value added reseller in the UK helping small and medium-sized businesses to procure the right hardware and software. Softcat operates as an extension of the sales forces of its vendor partners and an extension of the IT departments of its customers, making itself an indispensable part of the value chain.
Gross profit, the industry’s key metric for top-line growth, has been compounding at a double-digit rate for over 20 years, and we see this level of growth as sustainable as businesses prioritise technology investment to remain competitive.
Simplistically, the market’s narrative over the past year has been that IT resellers will become less relevant in the age of AI as firstly, traditional vendors like Microsoft lose market share to AI native vendors who will sell directly to companies and secondly, clients query AI for advice and then AI agents take over the procurement process.
Despite this narrative, Softcat’s business has gone from strength to strength, validating its key role in the supply chain. In its most recen[AP3.1]t market update, the company announced that demand for its products and services remains strong as client investment in AI-related infrastructure accelerates. And, importantly, its ability to meet this demand remains high despite growing shortages of hardware components, thanks to long-dated relationships with vendors.
Management expects mid-teens annual profit growth, up from high single digit earlier in the year, and recent industry data suggests that this strong performance might continue into the next financial year.
Softcat’s share price has increased 60% over the past couple of months. The market is now rewarding its strong financial performance, and disproving the narrative of disruption as evidence surfaces that AI companies such as Anthropic and OpenAI are exploring relationships with key resellers.
Reply
Reply began operating in 1996 with the goal of helping large Italian corporations embrace new technologies. Since then, as technology progressed, so did Reply’s expertise. This ability to adapt has earned the company the reputation of a trusted partner that clients can rely upon throughout their digitalisation journey.
Reply is positioned at the intersection of human talent and artificial intelligence. Rather than treating AI as a threat to its consulting model, Reply has organised itself as a network of small, agile, highly specialised competence centres that can absorb new technologies quickly and turn them into client solutions - from agentic AI architectures to generative AI in content and digital experience. Its outcome-based client relationships and avoidance of commoditised work mean that as AI lifts productivity, freed-up client budgets tend to translate into new demand rather than shrinking engagements.
So far, Reply’s financial performance continues to support the Fairlight thesis with organic growth accelerating rather than slowing and margins expanding despite a challenging macro environment. In Q2 organic sales grew 8%, outpacing Q1’s growth of 7%. Earnings grew 20% which is impressive given that management is also investing for the future by launching a record number of boutiques. These strong results provided the catalyst for a positive share price reaction with the stock now up 50% over the past couple of months.
The Fairlight View
We consider Q2 to be another strong reporting season for the companies in the Fund with results supporting our aggregate EPS growth estimate of 13% for the portfolio in 2026. While the broader AI trade can provide some market volatility, we expect that share prices will continue to follow reliable earnings growth over the long term and are increasingly confident that the businesses in the portfolio are likely to be rewarded as they consistently demonstrate that AI is a tailwind to their competitive positions rather than a headwind.